The Hidden Retirement Trap: How Market Timing at the Wrong Moment Can Unravel Decades of Wealth
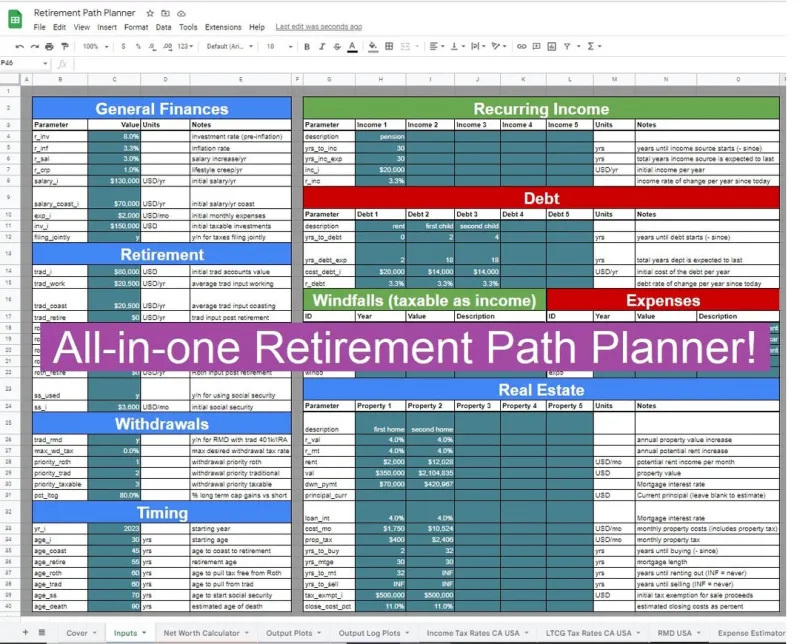
Photo: retirement portfolio planning calendar financial security, via i.etsystatic.com
Imagine two investors who each retire with $1 million. Both experience identical average annual returns of 6 percent over a 30-year retirement. Both withdraw $50,000 per year to cover living expenses. By conventional math, they should arrive at the same destination. But one finishes retirement with a comfortable nest egg still intact. The other runs out of money entirely by year 22.
The difference? The sequence in which their returns arrived.
This is the core of what financial professionals call sequence-of-returns risk — and for independent investors pursuing early retirement, it may be the single most underappreciated threat to long-term financial security.
Why Average Returns Can Be Dangerously Misleading
The arithmetic of investing is straightforward when no money is moving in or out of a portfolio. But the moment you begin making regular withdrawals — as every retiree must — the sequence of gains and losses begins to matter enormously.
Consider a simplified example. Suppose your portfolio earns returns of +25%, +10%, -15%, and -20% over four years in that order. Now reverse those returns: -20%, -15%, +10%, +25%. The average annual return is identical in both scenarios. But if you are withdrawing $50,000 per year throughout this period, the ending portfolio value differs dramatically. Early losses force you to sell a greater number of shares to meet withdrawal needs, permanently reducing the capital available to benefit from subsequent recoveries.
This asymmetry is precisely why a retiree who encounters a severe bear market in the first five years of retirement faces a fundamentally different challenge than one who encounters the same bear market in year 20.
The Historical Record Is Sobering
History offers several cautionary illustrations. An investor who retired at the beginning of 2000 — just as the dot-com bubble was cresting — would have faced back-to-back annual losses of approximately 9%, 12%, and 22% in the S&P 500 during their first three years of retirement. Even as the market eventually recovered and posted strong gains through the mid-2000s, the compounding damage inflicted during those early withdrawal years left many portfolios structurally weakened.
Similarly, an investor who retired in late 2007, just before the financial crisis erased roughly 50% of equity values, faced a scenario where every withdrawal during the downturn was made at deeply depressed prices. The subsequent decade-long bull market helped those who remained invested, but for those withdrawing steadily, the recovery was never fully captured.
Early retirement amplifies this risk considerably. A traditional retiree at 65 has perhaps a 25 to 30-year time horizon. An investor retiring at 50 may need their portfolio to sustain withdrawals for 40 years or more — a much longer runway across which adverse sequences can compound.
Rethinking the Standard Withdrawal Framework
The widely cited 4% rule — which holds that withdrawing 4% of your initial portfolio annually provides a high probability of lasting 30 years — was derived from historical US market data and has genuine merit. However, research suggests that for retirement horizons extending beyond 30 years, the safe withdrawal rate may need to be adjusted downward, particularly when valuations are elevated at the time of retirement.
For the independent investor, rigid adherence to a fixed withdrawal rate represents its own form of risk. A more adaptive approach acknowledges that market conditions fluctuate and that withdrawal strategy should flex accordingly.
Strategy One: Dynamic Withdrawal Adjustment
Rather than withdrawing a fixed dollar amount each year regardless of market performance, dynamic withdrawal strategies tie annual distributions to portfolio performance. In years when the market delivers strong returns, withdrawals may increase modestly. In years marked by declines, withdrawals are trimmed — perhaps by 10 to 15 percent — to allow the portfolio to recover more effectively.
This approach requires some flexibility in lifestyle spending, but for investors who have built discretionary versus non-discretionary expense clarity into their financial plan, it is a highly effective buffer against sequence risk. The core principle is straightforward: spend less when your portfolio is under stress, and you preserve more capital for the inevitable recovery.
Strategy Two: The Bucket Framework
The bucket strategy divides a retirement portfolio into distinct segments based on time horizon and purpose. A typical three-bucket structure might look like this:
- Bucket One (Years 1–3): Cash and short-term Treasury securities sufficient to cover two to three years of living expenses. This bucket is never exposed to equity market volatility and ensures that withdrawals can be funded without selling equities during a downturn.
- Bucket Two (Years 4–10): Intermediate-term bonds, dividend-paying equities, and other income-generating assets. This bucket provides a bridge between the immediate cash reserve and the long-term growth portfolio.
- Bucket Three (Years 10+): A broadly diversified equity portfolio oriented toward long-term capital appreciation. Because this bucket will not be touched for at least a decade, it can weather significant short-term volatility without forcing ill-timed liquidation.
The bucket structure is particularly valuable psychologically. During a market downturn, an investor drawing from Bucket One knows that their immediate financial needs are met regardless of what equities are doing. This reduces the temptation to panic-sell and allows the long-term portfolio to recover intact.
Strategy Three: Adjusting Equity Exposure Around Retirement
Conventional wisdom has long recommended gradually reducing equity exposure as retirement approaches. More recent thinking has introduced the concept of a rising equity glidepath — actually reducing equity exposure slightly in the years immediately before and after retirement, then gradually increasing it again as the portfolio ages.
The logic is counterintuitive but sound. The years surrounding the retirement date represent the period of maximum vulnerability to sequence risk. Lowering equity exposure during this window reduces the potential damage from an early bear market. As the portfolio ages and the impact of early returns diminishes, equity exposure can be rebuilt to support long-term growth.
Building a Sequence-Resilient Portfolio
Beyond withdrawal strategy and asset allocation, several additional tools can meaningfully reduce sequence risk:
Maintain a dividend income layer. Portfolios with meaningful dividend income can fund a portion of annual withdrawals without requiring asset sales. When markets decline, dividend income continues to flow, reducing the number of shares that must be liquidated at depressed prices.
Consider a modest bond ladder. A series of individual bonds maturing in successive years provides predictable cash flow that is independent of equity market performance, reinforcing the cash buffer in Bucket One.
Delay Social Security if possible. For investors who retire early, delaying Social Security benefits until age 70 maximizes the guaranteed monthly income that will eventually offset portfolio withdrawals. Every dollar of guaranteed income reduces dependence on portfolio distributions during the high-risk early retirement years.
The Investor's Takeaway
Sequence-of-returns risk is not a theoretical concern. It is a structural feature of retirement finance that has ended the financial independence of investors who, by any reasonable measure, had saved enough. The independent investor who understands this risk — and builds their withdrawal strategy, asset allocation, and income architecture around it — stands in a fundamentally stronger position than one who relies solely on historical average returns.
The goal is not to eliminate market risk. It is to ensure that a bad sequence of early returns does not become a permanent and irreversible event. With thoughtful planning, it does not have to be.