The Inflation Tax on Your Investment Returns: A Framework for Protecting Real Wealth
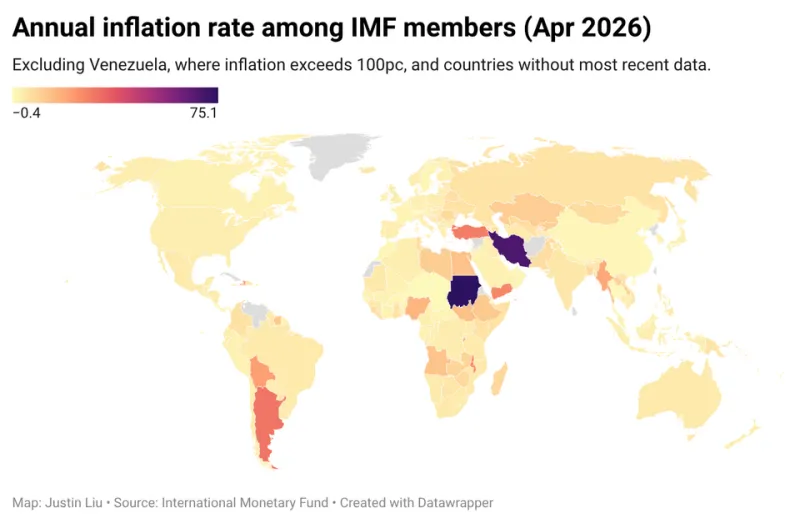
Photo: JJLiu112, CC0, via Wikimedia Commons
There is a number that appears on virtually every brokerage statement, every financial planning projection, and every retirement calculator used by American investors. It is the nominal return — the raw percentage gain on a portfolio before any adjustment for the rising cost of living. And for most investors, it is the only number that receives serious attention.
This is a costly oversight.
When inflation runs at 4%, a portfolio returning 7% annually is not growing at 7%. In real terms — in terms of actual purchasing power, of what that money can buy — the portfolio is growing at approximately 3%. The other 4 percentage points are not profit. They are compensation for the silent, continuous erosion of the dollar's value. Understanding this distinction is not merely academic. It reshapes how an investor should evaluate every asset class, every strategy, and every benchmark.
Nominal vs. Real: The Number That Actually Matters
The real rate of return is calculated using a straightforward formula: subtract the inflation rate from the nominal return. More precisely, economists use the Fisher equation — (1 + nominal rate) ÷ (1 + inflation rate) − 1 — but for practical purposes, simple subtraction provides a workable approximation.
The implications are significant. Consider a conventional intermediate-term bond fund yielding 5% during a period when the Consumer Price Index is rising at 4.5%. On a nominal basis, the investor is earning a positive return. On a real basis, they are barely breaking even — and after federal income taxes on interest income, they are almost certainly falling behind. This is not a hypothetical scenario. It is a description of conditions that prevailed in the United States during much of 2022 and into 2023, a period during which millions of investors in traditional fixed-income allocations experienced meaningful negative real returns without fully recognizing it.
Why Conventional Bond Allocations Deserve Scrutiny
The standard advice for managing portfolio risk has long centered on a stock-bond split — equities for growth, bonds for stability. This framework has genuine merit during periods of low and stable inflation. But it contains a structural vulnerability that inflation exposes ruthlessly.
Fixed-rate bonds are, by their nature, promises to deliver a specific nominal cash flow. When inflation rises, the purchasing power of those future cash flows declines. The bondholder has no contractual protection against this erosion. A 10-year Treasury note purchased at a 3% yield in a 1% inflation environment provides a healthy real return. The same note, held as inflation climbs to 5%, delivers a deeply negative real return — even as the nominal yield remains unchanged.
For independent investors who have allocated substantial portions of their portfolios to traditional fixed income in the belief that bonds are inherently conservative, this dynamic represents a risk that standard volatility measures do not capture.
Treasury Inflation-Protected Securities: The Structural Hedge
Treasury Inflation-Protected Securities, commonly known as TIPS, are US government bonds whose principal value adjusts in line with the Consumer Price Index. When inflation rises, the principal increases; when inflation falls, it decreases. Interest payments, which are calculated as a fixed percentage of the adjusted principal, therefore rise alongside inflation.
For independent investors seeking direct inflation protection within a fixed-income allocation, TIPS offer a structurally sound solution. They are backed by the full faith and credit of the US government, carry no credit risk, and provide a guaranteed real yield — which is stated at the time of purchase.
TIPS are available directly through TreasuryDirect.gov or through mutual funds and exchange-traded funds that hold diversified portfolios of inflation-protected securities. The latter approach provides liquidity and simplicity, though investors should be aware that TIPS funds carry interest rate risk and can experience short-term price volatility even as they protect against inflation over time.
One nuance worth understanding: TIPS pay taxes on both the interest income and the inflation adjustment to principal each year, even though the principal adjustment is not received in cash until maturity. Holding TIPS within tax-advantaged accounts — IRAs or 401(k)s — eliminates this so-called "phantom income" problem and is generally the preferred approach for taxable investors.
Real Assets: Equity Exposure to Tangible Value
Beyond inflation-protected bonds, a category of investments broadly referred to as real assets has historically demonstrated meaningful inflation-hedging characteristics. This category includes:
Real Estate Investment Trusts (REITs). REITs own income-producing properties — apartment complexes, commercial buildings, industrial warehouses, data centers — whose rents tend to rise with inflation. REITs are required to distribute at least 90% of taxable income to shareholders, providing an income stream that can keep pace with rising prices. Publicly traded REITs offer the liquidity of stock market securities without the capital requirements of direct property ownership.
Commodities and commodity-linked equities. Raw materials — oil, natural gas, agricultural products, industrial metals — are themselves inputs into the inflationary process. When prices rise broadly, commodity prices frequently lead the way. Investors can gain exposure through commodity ETFs, or through equities in energy, mining, and agriculture sectors. The latter approach combines inflation sensitivity with the earnings growth potential of operating businesses.
Infrastructure. Regulated utilities, toll roads, airports, and pipelines often operate under contracts or regulatory frameworks that allow for price increases tied to inflation indices. Infrastructure-focused funds and ETFs provide access to this inflation-linkage with diversified exposure across operators and geographies.
Sector Rotation as an Inflation Response Tool
Within the equity portion of a portfolio, not all sectors respond to inflation equally. Historically, energy, materials, and certain financial services sectors have tended to outperform during periods of rising inflation, while rate-sensitive sectors such as utilities and consumer staples — and particularly long-duration growth equities — have faced headwinds.
The independent investor need not attempt to predict inflation precisely. Rather, a measured tilt toward inflation-sensitive sectors during periods when inflation trends are rising, and a rebalance toward growth-oriented sectors when inflation moderates, represents a disciplined form of tactical allocation that can meaningfully improve real returns over a full market cycle.
This is not market timing in the pejorative sense. It is a systematic response to macroeconomic signals — the kind of evidence-based adjustment that distinguishes thoughtful portfolio management from passive complacency.
Building a Real Return Framework
The practical application of these concepts begins with a simple discipline: evaluate every investment on a real, after-tax, after-inflation basis. This means:
-
Establish a real return target. If your financial plan requires 5% annual real growth to meet long-term objectives, nominal returns of 5% during a 4% inflation environment do not satisfy that requirement. Adjust expectations and allocations accordingly.
-
Audit your fixed-income exposure. Identify the proportion of your bond allocation in fixed-rate instruments and assess the real yield those instruments provide at current inflation levels. Consider whether a partial reallocation to TIPS or floating-rate instruments is warranted.
-
Introduce real asset exposure deliberately. A 10 to 20% allocation to REITs, commodities, infrastructure, or inflation-sensitive equities can provide meaningful portfolio-level inflation protection without dramatically altering the overall risk profile.
-
Account for taxes. Inflation protection that generates fully taxable ordinary income may be less effective in practice than it appears on paper. Placement within tax-advantaged accounts maximizes the after-tax real return of inflation-sensitive assets.
The Wealth-Building Imperative
Inflation is not an extraordinary event. It is the default condition of a modern economy, and it has been a persistent feature of American financial life for generations. The investor who builds a portfolio optimized for nominal returns alone is, in effect, running a race while ignoring the headwind.
Real wealth — the kind that translates into actual purchasing power, financial independence, and lasting security — is built by investors who account for inflation at every stage of their planning. The strategies outlined here are not complex. But they require a deliberate shift in perspective: from nominal to real, from surface-level returns to the numbers that actually determine whether your wealth is growing or quietly shrinking.